Wine is said to be dying because people are drinking less. The trend is real, but the aggregate hides what is actually happening.
The first question is whether there is overproduction. Not all wine produced in a year is drunk in that year, but over several years production should broadly equal consumption. Otherwise, a pile of undrunk wine builds up. World production still exceeds consumption, but the gap is much smaller than it used to be. In 2025, the International Organisation of Vine and Wine (OIV) estimates production at 227 million hectolitres and consumption at 208 million hectolitres, a gap of about 19 million hectolitres, against 64.7 million hectolitres in the late 1980s. Since then, production has fallen by about a quarter and consumption by only about an eighth. The gap has narrowed, but it has not closed. Production is currently held down by several consecutive poor harvests, rather than by structural adjustment, so a normal vintage would widen it again.
More importantly, the aggregate hides the real imbalance. The world does not have too much wine so much as too much of one kind: inexpensive, undifferentiated wine. When demand falls while production remains high, prices suffer, particularly at the lower end of the market, where wine is treated as a commodity rather than a differentiated product.
People have been drinking less for decades. Europe, historically the centre of wine consumption, shows the trend clearly. In 1960, France consumed about 127 litres per person per year, Italy 108 and Spain 51. By 1999, France was at 58.7 litres, Italy at 54.2 and Spain at 39.5. By 2022–23, consumption was roughly 45–47 litres in France, 42–44 in Italy and 24–25 in Spain. In other words, France and Italy have lost roughly 60% of their per capita consumption since 1960, and Spain about half.
Populations outside Europe are growing, but the question is whether wine will become part of the general food culture or remain a product for an elite. China was once seen as the great new frontier for wine consumption, and for a time it seemed to justify that optimism. In 2017, the country consumed 19.3 million hectolitres, making it one of the world’s largest wine markets. Since then, however, consumption has collapsed. By 2024, it had fallen to just 5.5 million hectolitres, a decline of roughly 72% in seven years. The OIV’s figures show the decline almost continuously, from 19.3 million hectolitres in 2017 to 17.6 in 2018, 15.0 in 2019, 12.4 in 2020, 10.5 in 2021, 9.1 in 2022, 6.8 in 2023 and 5.5 in 2024. China may still be an important market for the world’s finest wines, particularly the Grands Crus of Burgundy and Bordeaux, but its experience is a warning against assuming that growing populations will automatically create new mass markets for wine.
Tastes have also changed. Wine lists in trendy London restaurants would once have been dominated by French wines; today they take you to Georgia, Slovenia, Hungary or countless other regions. Even Barolo, traditionally described as the King of Wines, historically struggled to find buyers, as David Gleave describes in Barolo & Barbaresco: The Primacy of the Vine. This seems almost unimaginable today. Consumers now have an appetite for a much broader diversity of wine, creating dynamic competition against the traditional regions. Bordeaux is perhaps the clearest example. Its problem is not only that people are drinking less wine, but that they are drinking less of the type Bordeaux has historically produced in enormous quantities.
The closest parallel is the crisis of the Swiss watch industry in the 1970s. The recently developed quartz movement threatened the traditional mechanical movement by creating something that could tell the time for a fraction of the price. Swiss watchmakers were hit extremely hard, and employment in the Swiss watch industry fell from around 90,000 people in 1970 to just over 30,000 by 1984. A large number of companies disappeared.
What several Swiss watchmakers eventually understood was that quartz was particularly effective at the lower end of the market. The expensive watches were not going to be replaced in the same way by a battery powered movement. People were willing to pay for craftsmanship, heritage and mechanical complexity. The lower end, on the other hand, was much harder for traditional Swiss manufacturers to defend. The result was a dramatic consolidation of the industry. While the Swiss watch industry is today stronger than it was during the crisis, it has also shifted much more towards the high end of the market.
The lesson for winemakers may be to stop defending the lower end. The picnic wines worth a couple of euros are a category that should disappear altogether. In some regions such as Bordeaux, this has already started. France has introduced large scale vine grubbing schemes, the subsidy is paid per hectare and the scheme is voluntary, so growers are likely to pull the parcels that lose them the most money. In practice this seems to mean high yield land producing generic Bordeaux, not the gravel slopes and plateaux behind the famous names. The restructuring does not stop at the vines. Gironde’s vineyard area fell by around 20,000 hectares between 2023 and 2025, while a new €20 million land fund has been created to buy or exchange parcels left behind by the uprooting and redirect them towards other agricultural uses.
This looks like decline, but it is also an attempt to reallocate land that no longer has a viable future in wine. It is not without risk, as critics argue that removing only part of an estate raises the per bottle cost of what remains.
People are drinking less, and new markets for cheap wine are not appearing automatically to replace the consumption lost in Europe. Trying to maintain production simply because vineyards have historically produced a certain volume of wine does not make much economic sense. The wine industry should take the Swiss lesson: rather than trying to convince people to drink more, convince them to drink better.
The future of wine is not about producing more bottles, but about producing fewer bottles that people are willing to pay more for. The artisanal, distinctive, mid to high end segment can offer something cheap wine cannot: a place, a producer, a vintage, a history and a reason to open the bottle. Drinking less does not mean the death of wine, only the death of cheap wine.
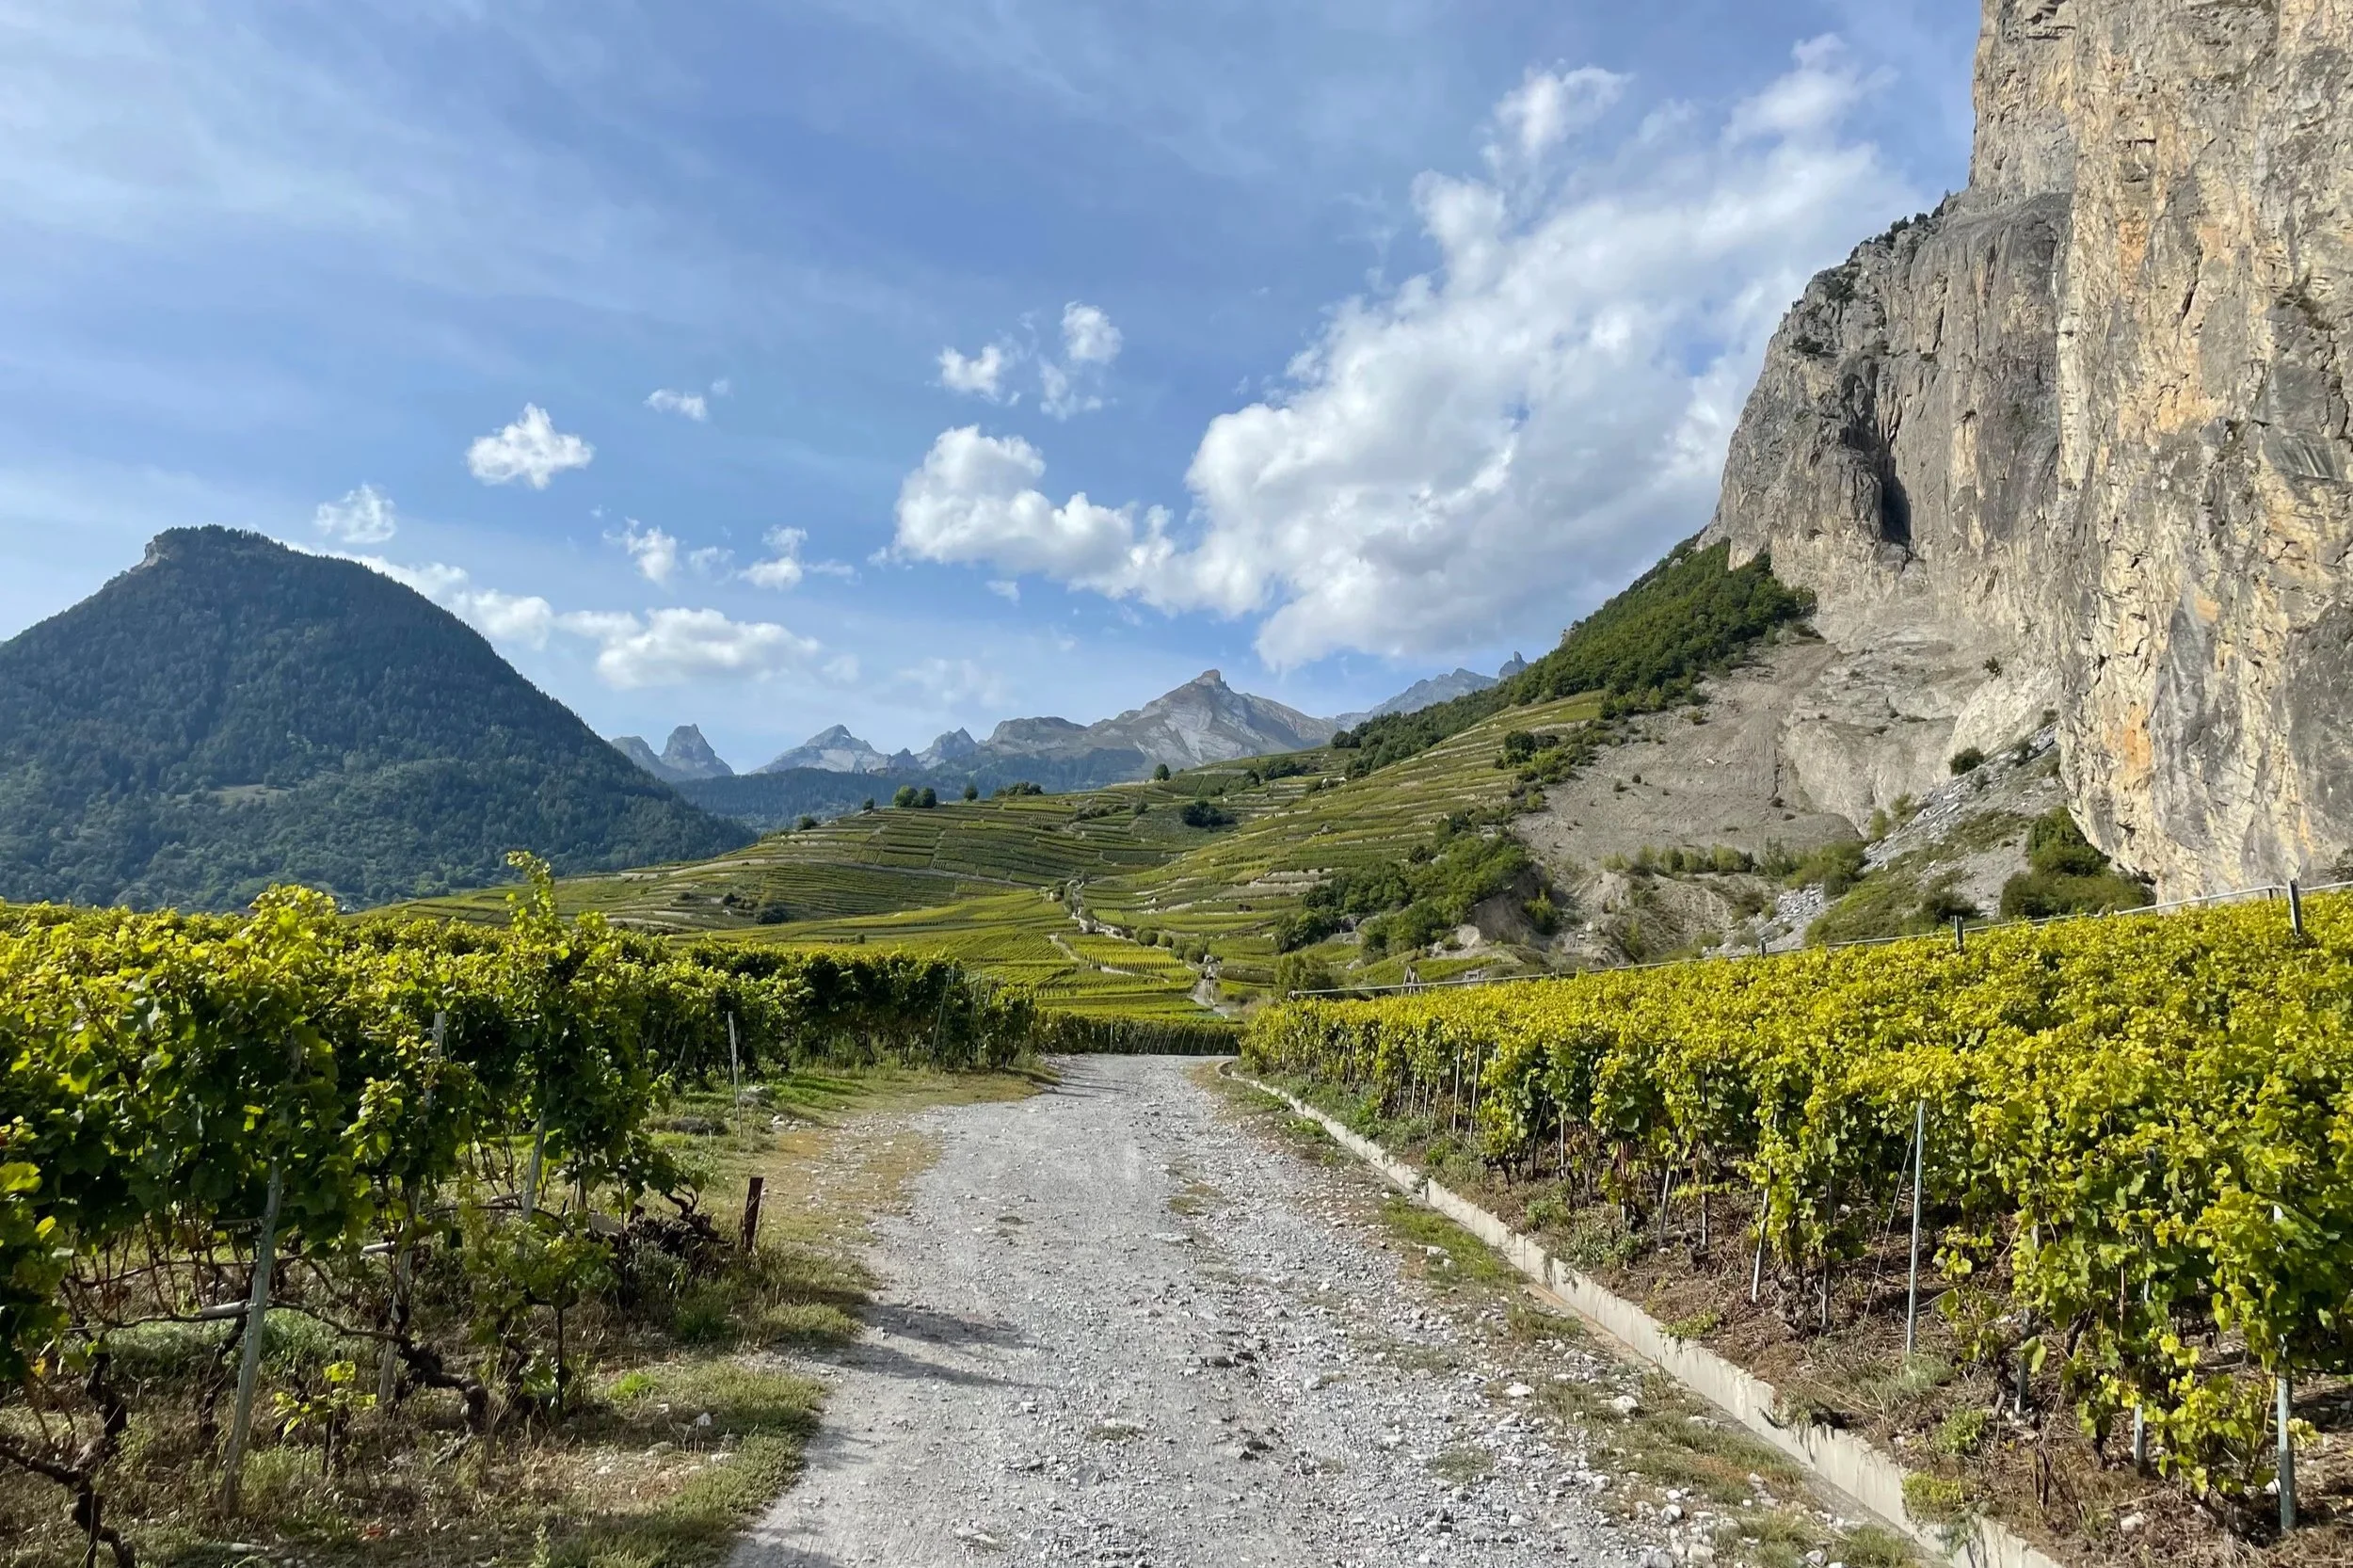
Chamoson, Switzerland, 2023.